How to Check and Improve Your CIBIL Score Before Applying for a Business Loan
Why your credit score matters for a business loan
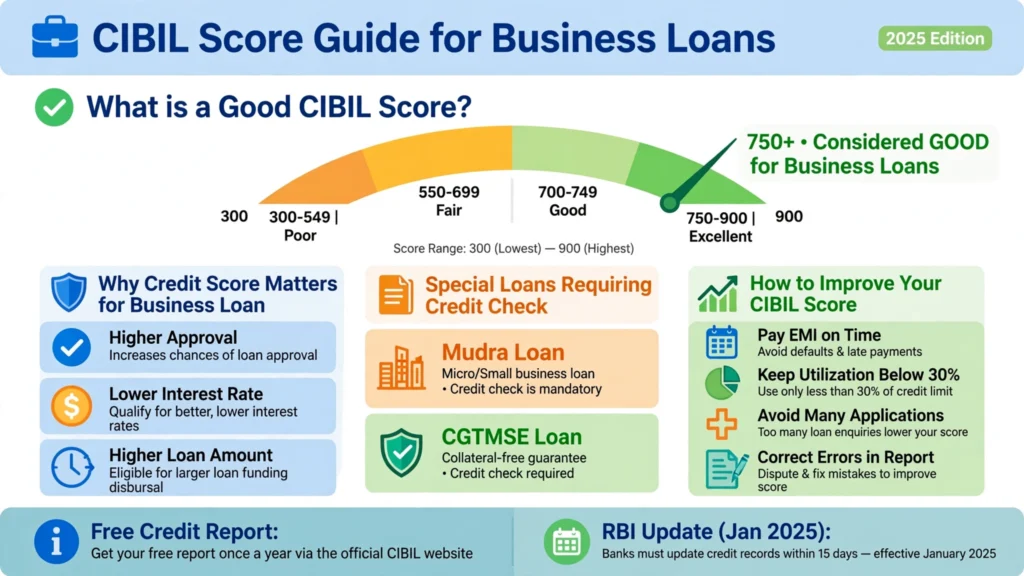
Banks and NBFCs check your credit score before lending, especially for small businesses where the owner’s personal credit history is closely linked to the business. A good score can mean:
- Higher chances of approval
- Lower interest rates
- Higher loan amounts
- Faster processing
Even government-backed loans like Mudra and loans covered by CGTMSE usually involve a credit check.
What is a good CIBIL score?
| Score range | What it generally means |
| 750–900 | Good to excellent; best chance of approval and better terms |
| 700–749 | Fair; approval possible, terms may vary |
| 650–699 | Weak; limited options, higher interest |
| Below 650 | Poor; approval difficult |
| NA or NH | No credit history (common for first-time borrowers) |
Each lender sets its own cut-offs. These ranges are only a general guide.
Personal score vs business credit rank
- Personal CIBIL score (300–900): based on your personal loans and credit cards. This matters most for proprietors and small business owners.
- CIBIL MSME Rank (CMR): a rank from 1 to 10 for businesses with business credit exposure, where 1 is the lowest risk. Companies and firms with business loans have a commercial credit report.
How to check your CIBIL score for free
- Visit the official CIBIL website (cibil.com) and choose the free annual report option.
- Register with your name, PAN, date of birth, mobile number and email.
- Verify with an OTP and answer the identity questions.
- Download your score and report.
You’re entitled to one free full credit report per calendar year from each credit bureau (TransUnion CIBIL, Experian, Equifax and CRIF High Mark). Many banks and apps also show your score for free.
RBI rules that help borrowers (from 1 January 2025)
| Rule | What it means for you |
| Faster updates | Credit bureaus update credit information every 15 days, so repayments and closures show faster |
| Free annual report | One free full credit report per year from each bureau |
| Reason for rejection | Lenders must tell you why your application was rejected based on credit information |
| Complaint resolution | Bureaus must resolve complaints within 30 days |
| Compensation for delay | ₹100 per day of delay to the borrower if complaints aren’t resolved on time |
9 practical ways to improve your CIBIL score
1. Pay every EMI and credit card bill on time
Payment history is the biggest factor. Even one missed payment can hurt. Set up auto-debit or reminders.
Try to use less than about 30% of your total credit card limit. If your limit is ₹1 lakh, keep your balance below ₹30,000 each month.
3. Don’t apply for many loans at once
Each loan or card application creates a hard enquiry. Many enquiries in a short time make you look credit-hungry.
Older, well-managed credit lines lengthen your credit history. Don’t close your oldest credit card without a good reason.
5. Maintain a healthy credit mix
A mix of secured loans (like a home or gold loan) and unsecured credit (like a credit card), all managed well, helps.
6. Clear overdue amounts and settle properly
Pay off overdue amounts in full. A loan marked “settled” (paid less than owed) looks worse than one marked “closed”. Where possible, pay the full amount and get it reported as closed.
7. Check your report for errors
Look for loans you never took, wrong overdue amounts, or closed accounts still shown as active. Raise a dispute on the bureau’s website. With the 30-day resolution rule, corrections are faster.
8. Be careful as a guarantor or co-borrower
If the main borrower defaults, your score is affected too.
9. Build credit if you have none
If you have no history, start small: a secured credit card against a fixed deposit, or a small gold loan, repaid on time.
How long does it take to improve a score?
Small improvements can show within one or two update cycles once errors are fixed or dues are cleared. Recovering from serious defaults takes longer, often months of consistent on-time payments.
Before you apply for a business loan: checklist
- Check your score and report from at least one bureau
- Correct any errors
- Clear overdue amounts and reduce card balances
- Keep business and personal transactions separate. Read our guide on separating personal and business finances.
- Prepare bank statements, ITRs, GST returns and Udyam registration
- Apply to one or two well-chosen lenders, not many at once
Frequently asked questions
What is the minimum CIBIL score for a business loan?
There’s no single rule, but many lenders prefer 700–750 or above. Some schemes and NBFCs lend at lower scores, often at higher interest.
Does checking my own CIBIL score reduce it?
No. Checking your own score is a soft enquiry and doesn’t affect it.
How often is my CIBIL score updated?
Under RBI rules effective January 2025, credit information is updated every 15 days.
Can I get a business loan with no credit history?
Yes, sometimes, especially for small Mudra loans or through SHGs, but having some credit history helps.
How do I correct an error in my CIBIL report?
Raise a dispute on the CIBIL website with supporting documents. Bureaus must resolve complaints within 30 days.
Sources (checked 28 October 2026)
- TransUnion CIBIL: cibil.com
- Reserve Bank of India, credit information reporting directions (effective 1 January 2025), as summarised by Godrej Capital
- RBI: rbi.org.in
Suggested internal links: Separate personal and business finances · PMEGP vs Mudra vs Stand-Up India · Free invoicing and accounting tools