Presumptive Tax Explained: Section 44AD, 44ADA and the New Section 58 for Small Businesses and Freelancers
What is presumptive taxation?
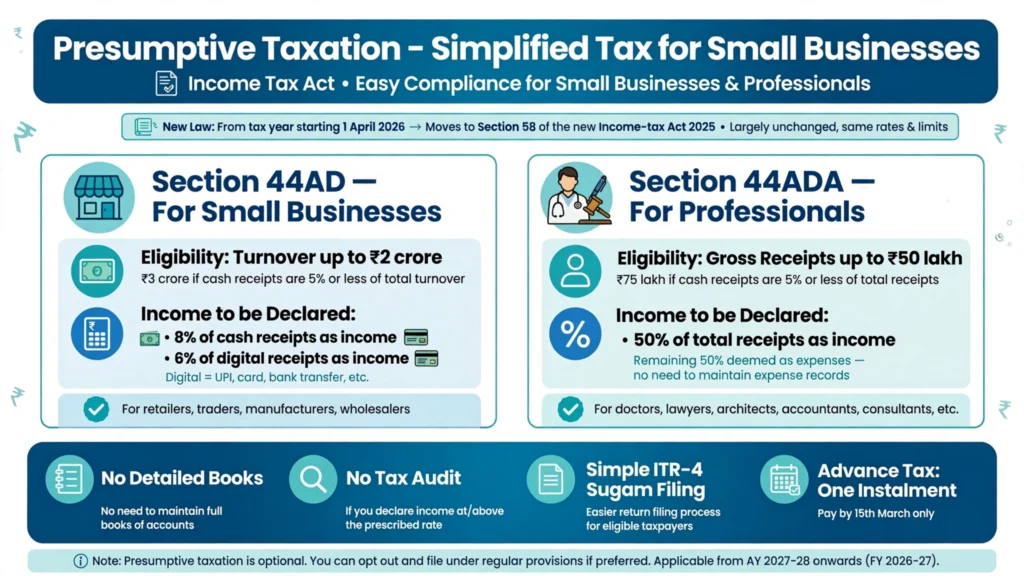
Normally, a business must keep books of accounts, calculate actual profit, and may need a tax audit. Presumptive taxation makes life simpler for small taxpayers: the law presumes your income is a fixed percentage of your turnover or receipts, and you pay tax on that.
Benefits
- No need to maintain detailed books of accounts (under these schemes)
- No tax audit if you declare at or above the presumptive rate
- Simple return filing, usually through ITR-4 (Sugam)
- Advance tax can be paid in one instalment by 15 March
Section 44AD: for small businesses
| Point | Details |
| Who can use it | Resident individuals, HUFs and partnership firms (not LLPs) |
| Turnover limit | ₹2 crore; ₹3 crore if cash receipts are 5% or less of total turnover |
| Presumptive income | 6% of turnover received through banking or digital modes; 8% of the rest |
| Who can’t use it | LLPs, people earning commission or brokerage, agency businesses, and specified professionals (they use 44ADA) |
| Lock-in | If you opt in and then opt out within 5 years, you can’t use 44AD for the next 5 years |
Example: A kirana store with ₹80 lakh turnover, of which ₹60 lakh came through UPI or bank and ₹20 lakh in cash.
- 6% of ₹60 lakh = ₹3.6 lakh
- 8% of ₹20 lakh = ₹1.6 lakh
- Presumptive income = ₹5.2 lakh (tax is calculated on this at your slab rate)
Section 44ADA: for professionals and many freelancers
| Point | Details |
| Who can use it | Resident individuals and partnership firms (not LLPs) in specified professions |
| Specified professions | Legal, medical, engineering, architecture, accountancy, technical consultancy, interior decoration and other notified professions |
| Receipts limit | ₹50 lakh; ₹75 lakh if cash receipts are 5% or less |
| Presumptive income | 50% of gross receipts |
| Lock-in | No 5-year lock-in like 44AD |
Example: A freelance software consultant earning ₹30 lakh, all through bank transfers, can declare ₹15 lakh as income.
Note for freelancers: whether your work counts as a “specified profession” (for example, technical consultancy) matters. Some freelance activities may fall under 44AD instead. Check with a CA. Read our guide to income tax for freelancers and the self-employed.
What changes with the new Income-tax Act, 2025?
The Income-tax Act, 2025 replaces the Income-tax Act, 1961 from 1 April 2026. Under the new Act:
- Presumptive taxation for business (old 44AD), goods carriages (old 44AE) and specified professions (old 44ADA) is combined into Section 58, in one table.
- The limits and rates described above continue in substance: ₹2 crore or ₹3 crore for business at 6% or 8%, and ₹50 lakh or ₹75 lakh for professions at 50%.
- The term “previous year” is replaced by “tax year”.
In practice:
- For income earned in FY 2025-26 (returns filed in 2026), the 1961 Act sections (44AD and 44ADA) apply.
- For income from 1 April 2026 onwards, refer to Section 58 of the 2025 Act.
The 5% cash condition explained
The higher limits (₹3 crore and ₹75 lakh) apply only if cash receipts are 5% or less of total receipts. Cheques and drafts that aren’t account-payee are treated as cash. If you take most payments through UPI, bank transfer or card, you’re likely to qualify for the higher limit.
When should you NOT use presumptive tax?
- If your actual profit margin is much lower than 6–8% (business) or 50% (profession), you may pay more tax than necessary. You can declare lower income, but then you may need to maintain books and get an audit.
- If you have large business losses you want to carry forward.
- If your business type is excluded.
Advance tax under presumptive taxation
Taxpayers under these schemes can pay their entire advance tax in one instalment by 15 March of the financial year. If you miss it, interest applies.
Frequently asked questions
What is the turnover limit under Section 44AD?
₹2 crore, or ₹3 crore if cash receipts are 5% or less of total turnover.
What is the presumptive income rate under 44ADA?
50% of gross receipts.
Can freelancers use Section 44ADA?
Freelancers in specified professions (such as technical consultancy or engineering) can. Others may need 44AD or regular taxation. Check with a CA.
Do I need to keep books of accounts under 44AD?
Not detailed books, if you declare income at or above the presumptive rate. Keep basic records of sales and bank statements anyway.
Which ITR form is used for presumptive income?
Usually ITR-4 (Sugam), if you meet its other conditions.
What is Section 58 of the Income-tax Act, 2025?
It’s the new section that combines the old presumptive taxation provisions (44AD, 44ADA and 44AE), applicable from 1 April 2026.
Can an LLP use presumptive taxation?
No. LLPs are excluded under both the old and the new provisions.
Sources (checked 28 October 2026)
- Income Tax Department: incometax.gov.in
- TaxGuru, “Analysis of presumptive taxation under Section 58 of Income-tax Act, 2025”
- TAXAJ, presumptive taxation guide (FY 2025-26)
Suggested internal links: Income tax for freelancers and self-employed · Separate personal and business finances · Free invoicing and accounting tools