Income Tax for Freelancers and Self-Employed in India: A Beginner’s Guide
Freelance and self-employed income in India is taxed differently from a salary, and the biggest thing most beginners miss is Section 44ADA — a presumptive taxation scheme that can save specified professionals significant time and, often, tax. Here’s what you actually need to know before you file.
Section 44ADA: The Presumptive Taxation Scheme
If you’re a specified professional — including medical practitioners, lawyers, engineers, architects, accountants, technical consultants, interior decorators, and certain other listed professions — Section 44ADA lets you declare 50% or more of your gross receipts as taxable income, without needing to maintain detailed books of accounts or undergo an audit.
The standard limit is gross receipts up to ₹50 lakh, extended to ₹75 lakh if at least 95% of your receipts come through digital payment channels (cash receipts must stay under 5%). Your actual expenses don’t need to be tracked or proven under this scheme — you simply declare 50% (or more, if you choose) as profit, and pay tax on that at standard income tax slab rates.
When You Must Move to Regular Filing Instead
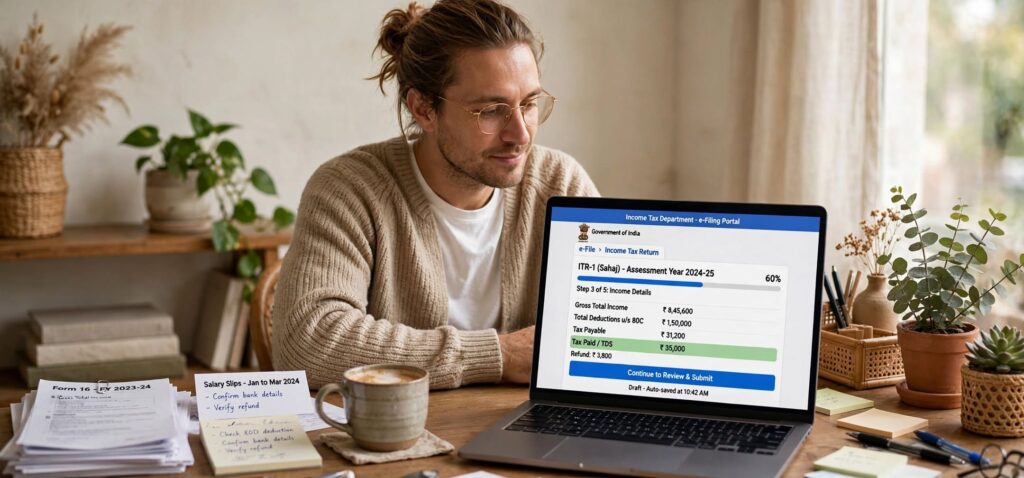
You’re required to maintain full books and undergo an audit if your receipts exceed the 44ADA threshold, or if your actual expenses are more than 50% of your receipts and you want to claim that higher deduction instead of the presumed 50%. In that case, regular ITR filing with full expense documentation becomes necessary rather than optional.
What Freelancers Not Covered by 44ADA Should Know
If your freelance work doesn’t fall under the specified professions list (for example, certain types of digital marketing, content creation, or consulting roles), you may fall instead under Section 44AD, a similar presumptive scheme for eligible businesses with its own threshold and deemed profit percentage — the mechanics are similar in spirit, but the eligibility and rates differ, so it’s worth confirming which section actually applies to your specific work.
Practical Filing Basics Every Freelancer Should Track
- Keep a simple running record of all income received, even if 44ADA means you don’t need full expense books
- Set aside advance tax quarterly if your total tax liability for the year is expected to exceed ₹10,000, to avoid interest penalties
- Track GST registration separately — income tax and GST are different obligations with different thresholds
- Keep bank statements and invoices for at least the period required for income tax record-keeping, even under presumptive taxation
Frequently Asked Questions
Do freelancers need to maintain detailed expense books in India?
Not if you’re eligible for and opt into Section 44ADA (specified professionals) or Section 44AD (eligible businesses) presumptive taxation, where you declare a fixed percentage of receipts as taxable profit instead of tracking every expense.
What’s the income limit for Section 44ADA?
₹50 lakh in gross receipts, extended to ₹75 lakh if at least 95% of your receipts are digital (cash receipts under 5%).
Do I still need to pay advance tax as a freelancer?
Yes, if your total estimated tax liability for the year exceeds ₹10,000, advance tax is generally required in quarterly instalments to avoid interest charges, regardless of whether you use presumptive taxation.